Short answer
Coverage for meth lab cleanup is uncertain and depends heavily on your policy form. Many homeowners and landlord policies contain pollution, contamination or intentional-act language that insurers may apply to drug residue, while some landlord forms or endorsements address tenant damage more directly. Sample first, report promptly, and ask the carrier for its written position before authorizing large removal work.
Why meth contamination is a hard insurance question
Methamphetamine residue is a chemical problem, not a fire or a flood. It settles invisibly on walls, ceilings, ductwork and soft materials, and it may only come to light when a tenant leaves, a buyer orders testing or law enforcement reports a seizure.
Insurers read that kind of loss through several parts of a policy at once. Pollution or contamination wording, exclusions for intentional or criminal acts, and conditions about occupancy can all come into play. The same facts might lead one carrier to deny and another to pay a portion, depending on the exact form and endorsements.
That is why the most useful first step is not guessing. It is getting the policy, reading the exclusions section with your agent, and asking the carrier to identify which language it is evaluating.
Owner-occupied vs rental: does it matter?
It matters a great deal. An owner-occupied homeowners policy is written for a household living in the property. A landlord or dwelling fire policy is written for a property rented to others, and some of these forms, or endorsements added to them, speak more directly to damage caused by tenants.
If you are a landlord, check whether your policy includes any coverage for malicious damage or tenant vandalism, and read how it defines those terms. Some carriers may treat contamination from drug manufacture differently from contamination caused by smoking, and some may exclude both. Your agent can tell you what your form actually says.
If you bought a home and later discovered it had been a lab, the issue may be less about your homeowners policy and more about the sale. Some states place disclosure duties on sellers. Minnesota, for example, requires sellers who know of meth production on a property to disclose it in writing before a sale, and buyers may sue for remediation costs within six years, according to the Minnesota Revisor of Statutes in 2024. A real estate attorney in your state can tell you what the seller owed you and how long you have to act.
Records the insurer needs
Meth claims are unusually document-driven, because the contamination cannot be seen. The adjuster will want evidence that residue exists, where it is, and how much of it exceeds whatever standard applies at your address.
Useful records typically include the following.
- Any law enforcement report, property notice or health department order related to the address.
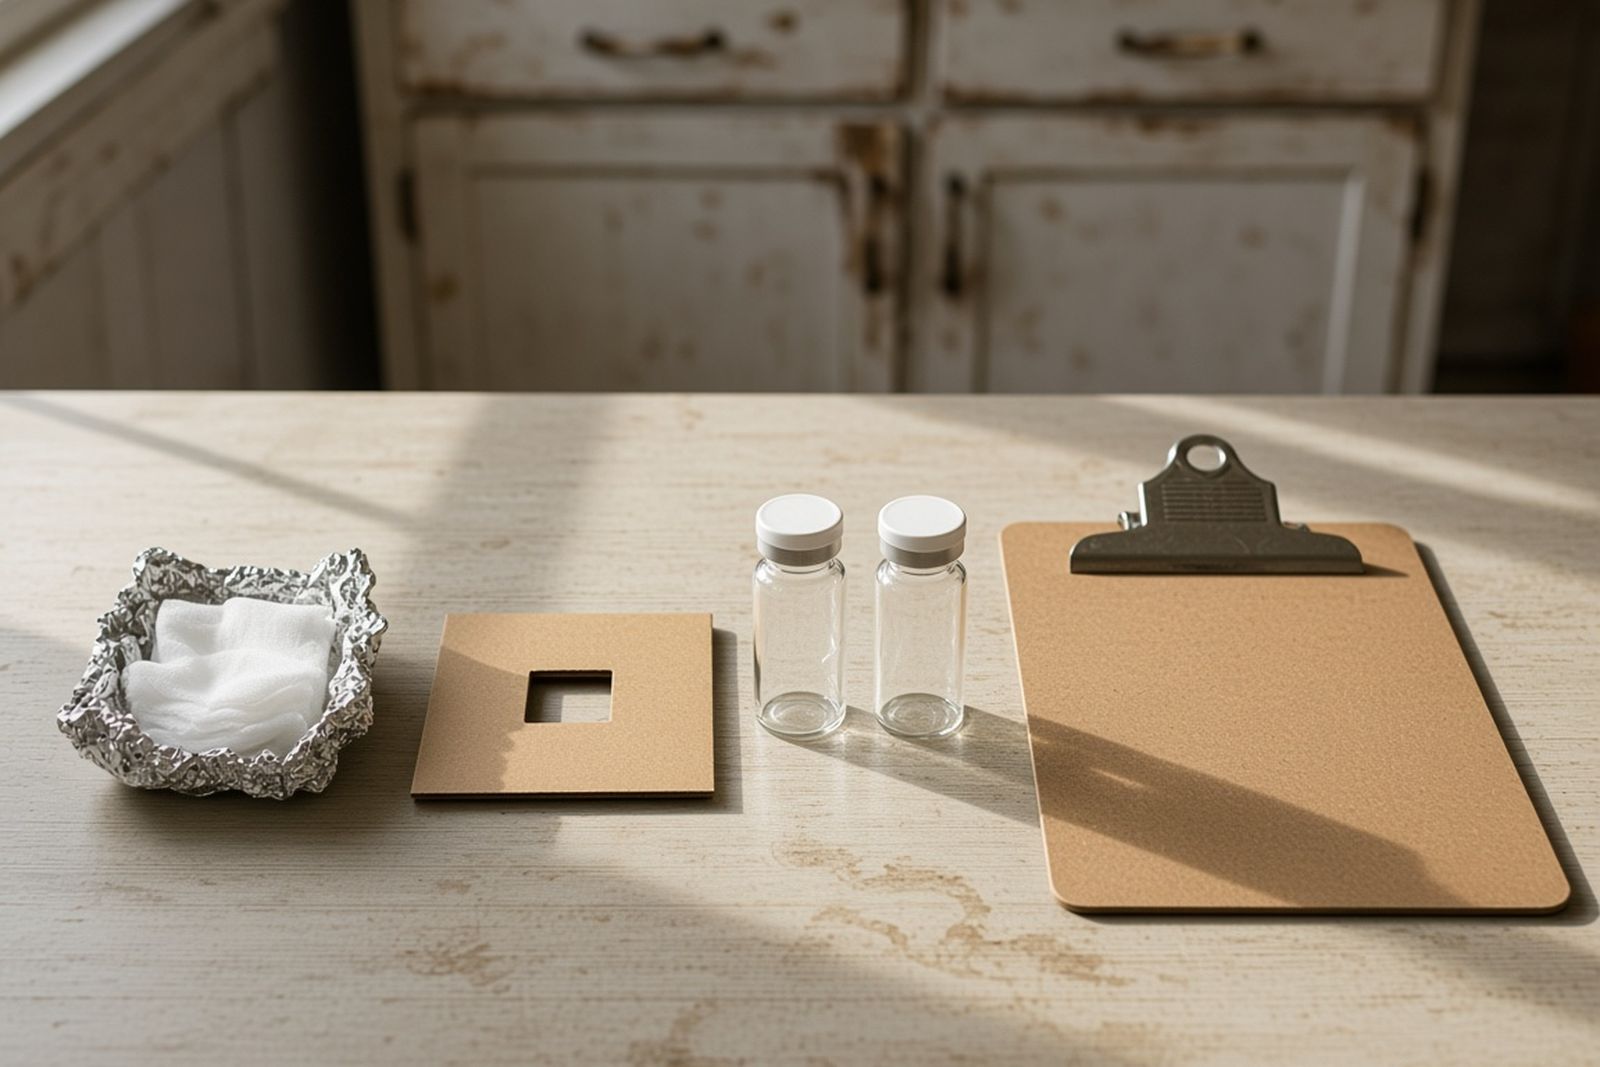
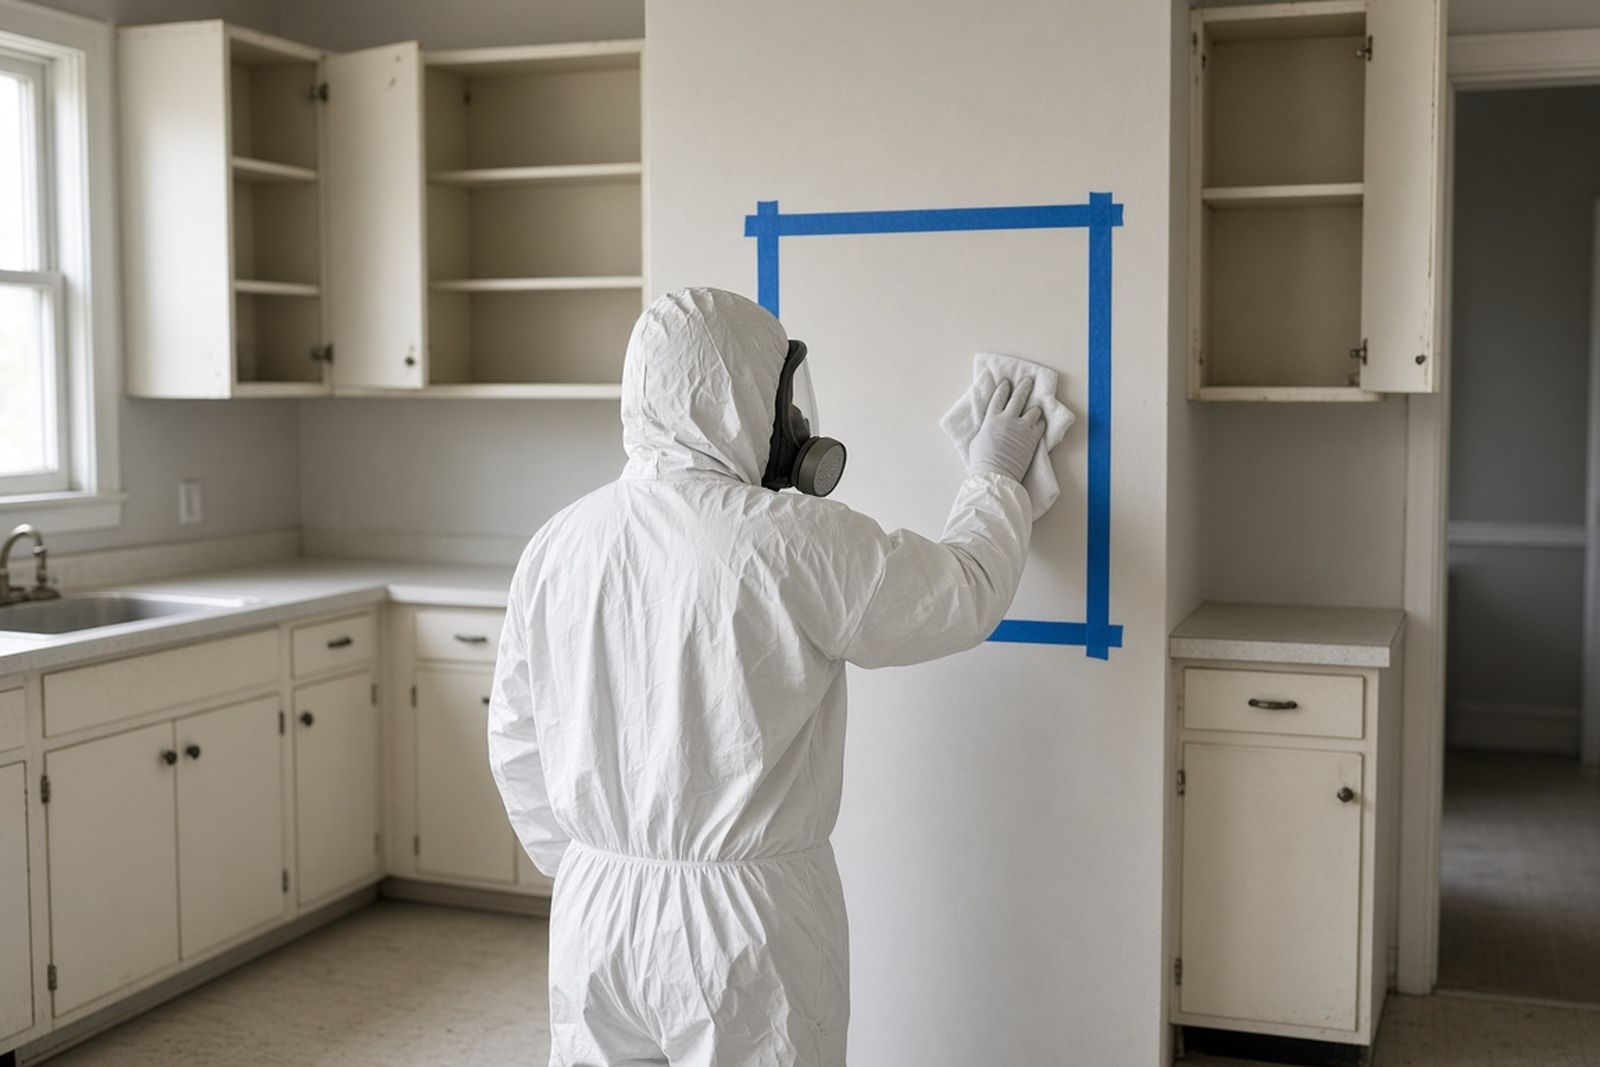
- Preliminary wipe sample results from an accredited laboratory, with a map of sampling locations.
- Chain-of-custody forms showing who collected and handled each sample.
- The written remediation work plan that separates cleaning, removal and HVAC work.
- Post-remediation clearance results showing the property met the applicable standard.
- Lease records, move-out dates and inspection notes if the property was rented.
How do sampling results affect the claim?
Numbers from an accredited laboratory give everyone something objective to discuss. Without them, the adjuster is weighing suspicion against suspicion.
The standard those numbers are compared against depends on where the property is. States that set a numeric surface limit do not all use the same one, and some have no limit at all. A result that requires full remediation in one state may call for less in another, so the adjuster needs to know which benchmark applies at your address.
Sampling design matters as much as the result
Sampling design matters as much as the result. Wipes taken from a single room tell the adjuster little about the rest of the house. A sampler who explains why they chose each location, such as the kitchen, the bedroom with stained ceilings and a return air grille, helps the carrier understand how far the problem reaches and which rooms may need no more than cleaning.
Composite samples, which combine wipes from several spots into one analysis, can reduce laboratory cost but make it harder to pinpoint the source. Ask the sampler how their method will affect the carrier's ability to separate heavily contaminated rooms from lightly affected ones.
Ask your sampler to state in the report which standard they compared results against and why. That sentence can save weeks of back-and-forth with an adjuster who is unfamiliar with the rules at your address.
An illustrative claim: the landlord who found out at turnover
This walk-through is a composite, built to illustrate the process rather than drawn from a real claim. A landlord inspects a single-family rental after the tenants move out and notices a chemical smell, stained ceilings in one bedroom and taped-over vents. A neighbor mentions that police visited the house months earlier.
The landlord keeps the house vacant and locked, calls their insurance agent and orders preliminary sampling from an independent sampler. Results from several rooms and the return air duct exceed the state standard.
The landlord's policy includes a tenant damage endorsement, but it also contains contamination language. The carrier asks for the lab results, the lease, the move-out inspection and the police report, then issues a written position covering part of the removal work and denying the rest.
In this illustration, the landlord pays the uncovered portion, keeps every record for future disclosure, and schedules clearance sampling before listing the unit again. A real carrier could decide differently in either direction. The point is that sampling and documentation made a decision possible at all.
What does cleanup cost, and why does it matter for the claim?
Carriers compare the estimate against the evidence, so a clear, itemized scope is more persuasive than a single total. Price depends on the size of the property, how far residue spread, which materials must be removed rather than washed, HVAC work, sampling and waste handling.
Any published average is only background. Historical figures from single state programs are years old and reflect local labor, disposal and sampling costs, so they cannot stand in for a quote on your property. The itemized scope for your address is what the adjuster will actually weigh.
Ask the contractor to price assessment, remediation and clearance testing as separate items. If the carrier accepts some items and not others, you will know exactly what remains your responsibility.
Five mistakes that weaken a meth lab claim
Well-meaning owners sometimes make choices that later make the claim harder to evaluate. Most of these come from wanting the property back in use quickly, which is understandable.
- Painting over walls or replacing carpet before sampling, which can hide evidence and may not reduce residue.
- Letting new tenants or family members move in before clearance results are available.
- Hiring one company to sample, clean and clear without checking whether your jurisdiction requires independent sampling.
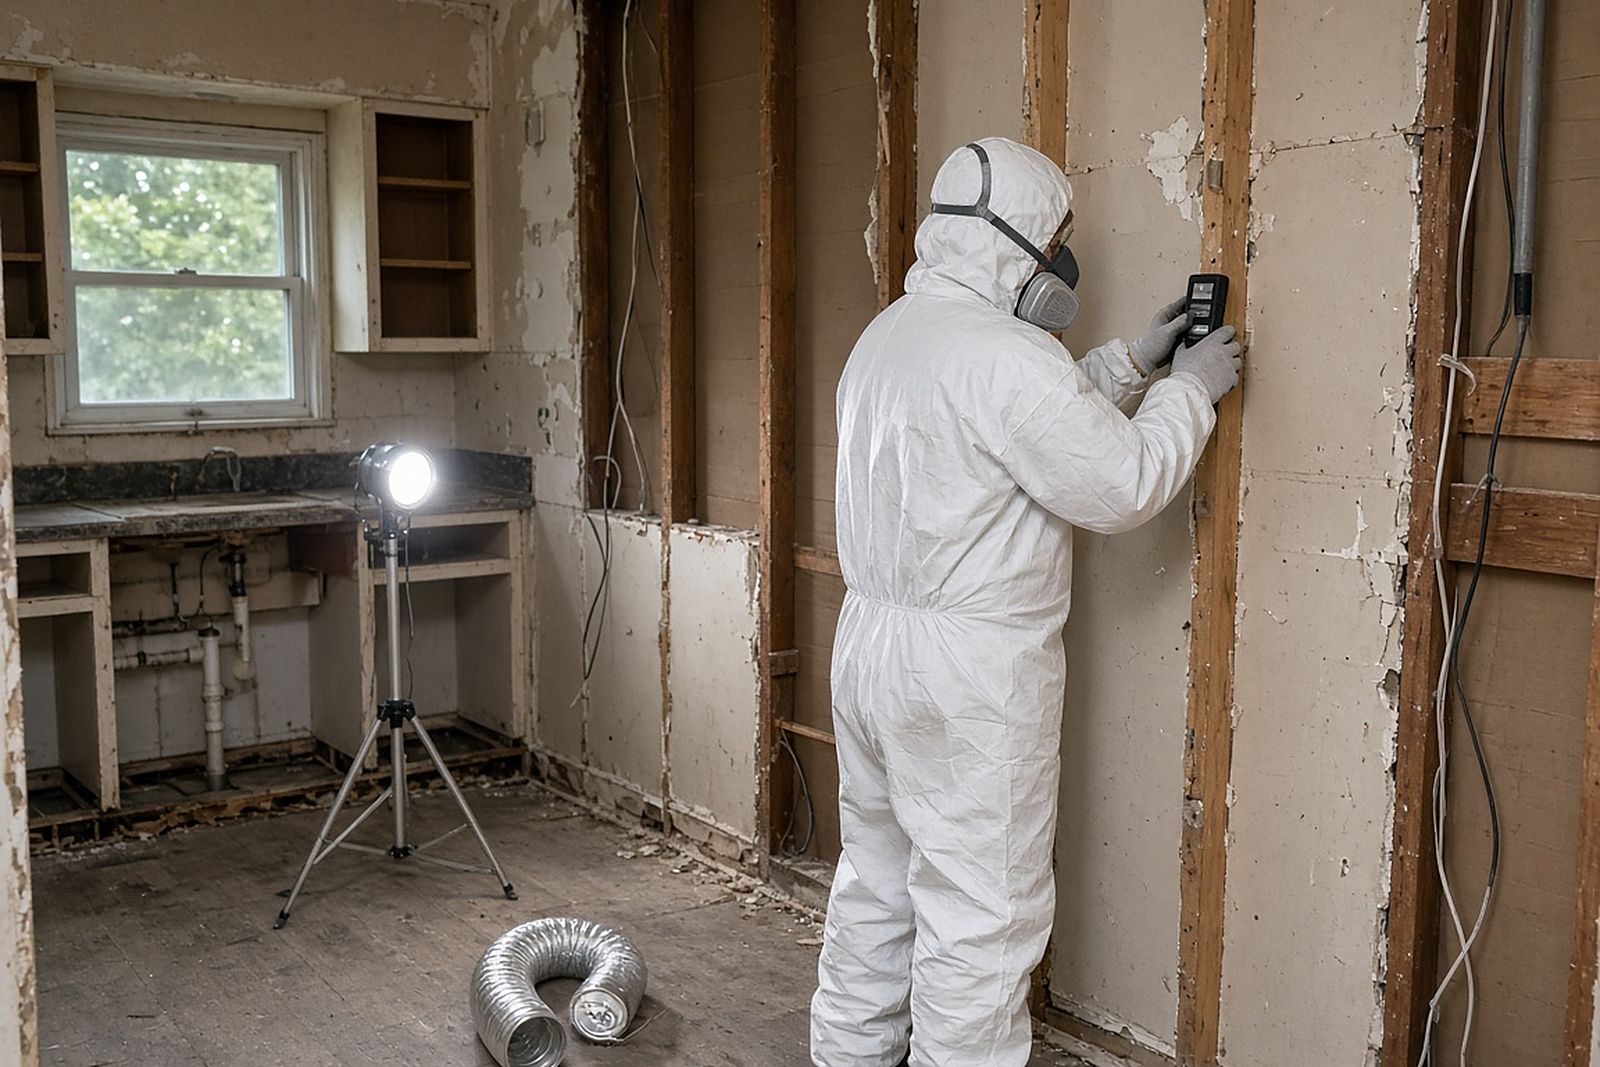
- Discarding items or cutting out drywall before the adjuster has had a chance to inspect.
- Relying on verbal assurances from anyone about what insurance will pay.
What if no insurance applies?
Many owners end up paying for some or all of the work themselves. That outcome is frustrating, but it does not mean the cleanup can be skipped or shortcut, especially if you plan to rent or sell the property.
Legal requirements also differ widely. The Legislative Analysis and Public Policy Association reported in 2025 that, as of April 2025, 18 states plus D.C. had no laws at all governing cleanup of properties contaminated by controlled substances. Where no statute applies, your county health department can still help you choose a defensible endpoint.
Other ways to recover costs
You may also have recovery options outside insurance, such as a security deposit, a claim against a former tenant, or a claim against a seller who failed to disclose known history. An attorney can tell you which are realistic where you live.
If the property is your home and you have been living in it without knowing its history, speak with your doctor about any symptoms that concern you, especially for young children. The cleanup and the claim can wait a day while you look after your household's health.
The order of steps
Keep the property unoccupied, call your agent to report the situation and request a copy of the full policy with all endorsements. Arrange preliminary sampling that fits your state's rules.
Share the results with the carrier, ask for a written coverage position, and only then authorize large-scale removal. Keep clearance reports permanently with the property records, because future buyers, lenders and tenants may ask for them years from now.
Finally, write a short timeline while the details are fresh: when you learned of the history, who you called, when samples were taken and when each decision arrived. Adjusters, attorneys and future buyers all find a dated summary easier to trust than memory.